

Acorns: Save & Invest Money
by Acorns
4.7
- Safety
- 100% Safe
- Category
- Finance
- Ratings
- 4.7
- Price
- Free
- Download
- 10.00M
This app is secure, reliable, free to install, and offers fast downloads without any risks or malware.
Screenshots
 Analysis by Getfullapps
I came away from Acorns with a fairly clear impression: it is designed to make investing feel like a background habit rather than a separate project. That idea is its biggest strength and also the reason it will not suit everyone. If you want a gentle way to start building an investing routine around stocks and ETFs, the app has an approachable structure. If you want complete control over every trade, detailed research tools, or a platform built mainly for active investing, I would look elsewhere.
As a finance app from Acorns, it focuses on financial wellness through a guided investing plan. The app is free to download, carries an Everyone age rating, and works on devices running at least iOS or Android version 10. Its scale is reassuring without being the main reason to install it: it has passed ten million installs, holds a 4.7 average from roughly 407,000 ratings, and has about 78,000 written reviews. Those figures suggest that the simple, habit-focused approach has connected with a large audience.
How Acorns turns investing into a routine
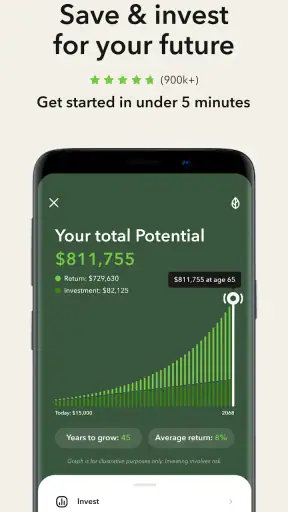
The first thing I noticed is that Acorns does not present investing as a task reserved for people who already understand markets. The central experience is built around choosing a smart investing plan for stocks and ETFs, then allowing that plan to do much of the organizational work. That can remove the intimidating first step of deciding what to buy, how to divide money, and when to act.
For a beginner, this matters more than a long list of technical tools. Many people do not avoid investing because they have no interest in it; they avoid it because opening a brokerage account, comparing funds, and making the first decision feels like too much responsibility. Acorns lowers that emotional barrier. I found its appeal strongest when I treated it as a system for consistency rather than a place to chase the best short-term opportunity.
The app’s approach also changes how I think about small amounts of money. Instead of waiting until I felt ready to make a large investment, I could view investing as something that fits alongside ordinary spending and saving habits. That does not make market risk disappear, and it does not guarantee a particular result, but it can make the behavior easier to maintain.
The most useful strength is not automation by itself; it is the reduction of decision fatigue. A user still needs to understand what is happening and choose a plan that matches their comfort level, but the app is structured to keep every investment decision from becoming a fresh research session. For someone who repeatedly intends to invest and then postpones it, that design can be more valuable than an advanced trading screen.
A practical everyday scenario
Imagine someone who receives a regular paycheck, pays rent and bills, and wants to begin investing but never has enough mental space to manage a portfolio manually. They might open Acorns during a quiet moment, work through the investing setup, and then let the selected plan become part of their broader financial routine. The important change is behavioral: investing no longer depends on remembering to research a stock after a busy day.
Articles to Explore Next

Uber Eats Makes Dinner Easier to Manage, but the Fees Add Up

Google Photos Turns a Camera Roll Into a Library You Can Find Your Way Through

Canva on Mobile: Adopt It for Quick Visuals, Test It for Demanding Work

Google Drive Keeps Work Moving Until It Doesn’t

Switching to Weather - By Xiaomi Means Relearning Your Forecast Routine

Ludo King and the Social Life of a Lucky Six
That scenario is especially relevant for people who are starting from zero. A traditional brokerage can offer more freedom, but freedom can feel like pressure when every choice is unfamiliar. Acorns gives the beginner a narrower path, which is helpful when the main challenge is getting started. The trade-off is that a narrower path is not ideal for someone who already knows exactly how they want to construct and manage a portfolio.
What the stocks-and-ETFs focus means in practice
Acorns is not simply a savings tracker with a market-themed interface. Its purpose is to connect a user with an investing plan centered on stocks and ETFs. That makes it more suitable for someone seeking long-term participation in the market than for someone who wants a high-speed trading workstation.
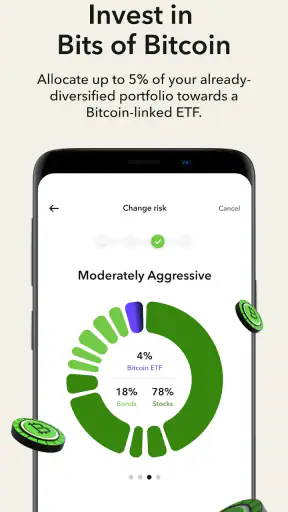
ETFs can provide a convenient way to gain exposure to a collection of investments, while stocks represent ownership in individual companies. A newcomer does not need to become an expert before exploring the app, but should still understand the difference between putting money into a diversified plan and selecting individual companies. The app can simplify the route into investing; it cannot remove the need to accept that values can rise and fall.
This is where I think the app should be judged fairly. Its simplicity is not evidence that investing is risk-free. It is a user-experience choice. Acorns helps organize the process, but the user remains responsible for deciding whether investing fits their goals, timeline, and ability to tolerate losses. I would not use the app as a substitute for an emergency fund or for learning the basics of market risk.
Small habits can be more important than constant checking
One subtle advantage of this style of app is that it discourages the urge to turn every market movement into an action. A beginner who checks a traditional trading platform repeatedly may be tempted to react to daily changes. A guided investing experience can instead keep attention on the habit and the plan.
That does not mean I would ignore an account forever. I would still review the selected plan, check whether my circumstances had changed, and make sure my contributions remained comfortable. The better workflow is periodic review rather than constant tinkering. In my experience, that distinction is important: an app can make investing easier, but a user can still undermine the benefit by treating it like a game of short-term predictions.
Where the experience becomes less convincing
The same simplicity that helps beginners can frustrate experienced investors. If I want to choose from a broad universe of securities, compare detailed research, place highly specific orders, or manage a carefully engineered allocation, Acorns feels intentionally limited. It is built around a guided plan, not around giving me every possible control.
That limitation is not automatically a flaw. A focused product can be easier to understand than a crowded brokerage interface. Still, prospective users should be honest about what they want. If the satisfaction comes from researching companies, adjusting positions, and making independent decisions, the app’s streamlined approach may feel restrictive after the initial novelty wears off.
There is also a psychological risk in making investing feel effortless. When money moves into an investment plan with little friction, it can be easy to forget that the money is exposed to market changes. I would want a new user to set a comfortable amount, keep enough cash available for near-term needs, and avoid treating the app as a guaranteed path to profit. Convenience should support good judgment, not replace it.
Another point worth considering is the difference between starting and optimizing. Acorns is persuasive as a starting point because it reduces complexity. It is less persuasive as a complete answer for someone whose financial life has become more complicated. A person balancing several goals, managing a detailed retirement strategy, or seeking sophisticated tax and portfolio control may eventually need tools beyond this app.
Questions I would answer before installing it
Is it suitable for a complete beginner? Yes, that is the audience I think will understand its design most quickly. The guided plan and emphasis on financial wellness are less intimidating than a platform that expects users to arrive with a trading strategy. I would still spend time learning what stocks and ETFs are and why values fluctuate, but I would not expect a beginner to master market terminology before opening the app.
Does free mean there is no financial decision involved? No. The app itself is free to download, but using an investing service still involves putting money at market risk and making choices about how much to invest. I would read the current in-app terms carefully before committing funds, and I would never invest money needed for rent, bills, or an imminent emergency.
Can it replace a full brokerage account? For some beginners, it may cover the basic investing experience they actually want. For an active investor or someone who needs extensive control, it is better viewed as a simpler alternative rather than a complete replacement. The right comparison is not “which app has more buttons?” but “do I want guidance or direct control?”
Will it help someone who struggles to invest consistently? This is where I see the clearest practical value. The app’s structure can turn a vague intention into a repeatable routine, especially for someone who tends to postpone decisions. My tip would be to review the plan at a calm time, choose an amount that does not strain the monthly budget, and then avoid changing course every time the market feels uncomfortable.
Is it appropriate for children? The Everyone rating means the app is broadly suitable from a content perspective, but that should not be confused with an automatic recommendation for every age or financial situation. Investing involves real money and real risk. A younger user would need appropriate adult guidance and an understanding of what the account is doing before using it.
Three ways to use it more thoughtfully
- Separate convenience from affordability. Before setting up a routine, I would look at ordinary cash-flow needs first. An easy investing habit is only helpful when the amount remains comfortable after essentials and short-term obligations.
- Use the guided plan as a learning framework. Rather than accepting a selection without thought, I would learn why the plan uses stocks and ETFs, what level of fluctuation I can tolerate, and how the plan fits my time horizon.
- Schedule reviews instead of reactions. I would check the account at sensible intervals and after major life changes, not make decisions solely because a market headline or a single bad day created anxiety.
These habits reveal an important trade-off. Acorns can reduce the number of decisions required to begin, but it cannot decide what financial priorities matter most to me. The app works best when I use its simplicity to stay organized while keeping personal responsibility in view.
How it compares with familiar alternatives
Compared with a standard self-directed brokerage, Acorns gives up breadth and control in exchange for a calmer starting experience. A traditional brokerage is usually the stronger choice for users who want to select individual investments, manage orders directly, and study a portfolio in detail. That flexibility is valuable, but it also places more responsibility on the user.
Compared with leaving spare money in a regular bank account, Acorns offers a route into market investing rather than simply holding cash. That can be useful for long-term goals, but a bank balance is generally easier to understand as short-term spending or emergency money. I would not treat the two options as interchangeable. The decision depends on when the money may be needed and how much fluctuation I can accept.
Compared with a budgeting app, Acorns is more focused on the investing side of financial wellness. A budgeting tool may be better for tracking categories, controlling spending, or planning bills. Acorns makes more sense after I have enough visibility over my cash flow to invest without creating a problem elsewhere.
Compared with a hands-on financial adviser, the app is more accessible and self-directed, but it does not replace personal advice tailored to a complicated situation. Someone dealing with major debt, unusual tax circumstances, or several competing financial goals may benefit from professional guidance before relying on an automated investing routine.
Who should choose it, and who should skip it
I would recommend Acorns to a first-time investor who wants a straightforward entry into stocks and ETFs, prefers a guided plan, and values consistency more than constant control. It is also a reasonable fit for a busy person who understands that investing is long term but has trouble turning that understanding into a regular habit.
I would be more cautious recommending it to someone with high-interest debt, no emergency cushion, or a need for the invested money soon. The app can make the act of investing feel simple, but it cannot make an unsuitable financial decision suitable. I would also point active traders, advanced portfolio builders, and research-focused investors toward a more flexible brokerage.
The developer, Acorns, has kept the product recognizable as a finance tool rather than trying to make it an all-purpose money dashboard. It was released in October 2014 and has continued to attract a substantial audience. The current version is 4.207.0, and that ongoing development matters because financial apps need a maintained experience to remain practical on modern devices.
After using it as a beginner-oriented investing tool, I see a product with a clear thesis: make participation easier by narrowing the number of decisions. That thesis works when the obstacle is hesitation. It works less well when the obstacle is a need for detailed control, sophisticated planning, or active research.
My final view is positive but deliberately limited. Acorns is a good choice for someone who wants to build a simple investing habit around stocks and ETFs and is willing to learn enough to use the plan responsibly. I would not call it the best platform for every investor, and I would not confuse its smooth experience with guaranteed results. For the right newcomer, though, Acorns: Save & Invest Money can turn investing from an intimidating project into a manageable part of everyday financial life.
Pros
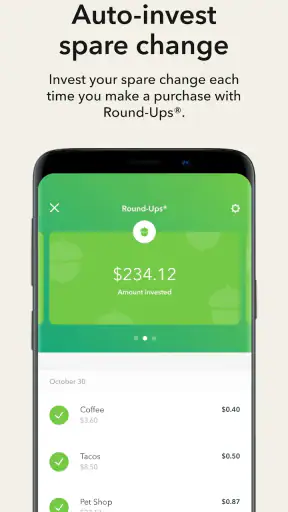
- Automatic round-ups make investing spare change effortless.
- Recurring deposits help build consistent saving habits.
- Diversified portfolios suit different risk preferences.
- Educational content makes investing easier for beginners.
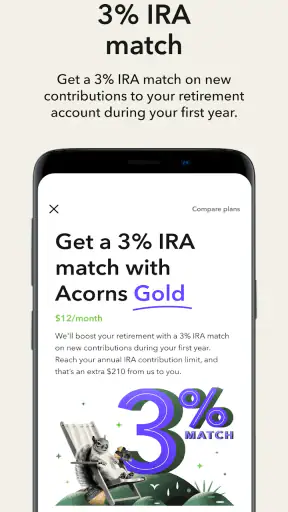
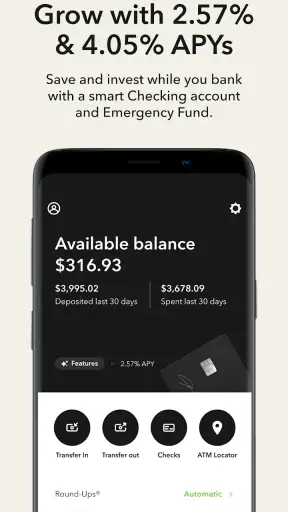
- Retirement and checking features add useful financial flexibility.
Cons
- Some features require a monthly subscription fee.
- Investment returns are not guaranteed and can lose value.
- Limited control may frustrate experienced investors.
- Account verification can take time before investing begins.
- Availability and features vary by country and eligibility.
FAQs for Acorns: Save & Invest Money
What is Acorns: Save & Invest Money, and how does it work?
Acorns is a personal finance and investing app designed to help users save and invest with minimal effort. Its main feature, Round-Ups, can round eligible purchases to the nearest dollar and invest the difference once the balance reaches the required threshold. The app also offers recurring investments, retirement accounts, checking features, and educational tools, depending on your plan and eligibility.
How much does Acorns cost, and is there a free version?
Acorns generally operates through paid subscription plans rather than offering a completely free long-term account. The price and included features can vary by plan, promotions, and location. Before subscribing, review the current fee schedule carefully because the monthly charge may be significant for users with a small balance. Some plans may include investing, retirement, banking, and family-oriented features.
Is my money safe when I use Acorns?
Acorns uses security measures such as encrypted data, account authentication, and identity verification to help protect user information. Investment accounts are generally subject to market risk and may have applicable brokerage protection, while banking features can have separate protections and conditions. These safeguards do not guarantee investment returns, prevent every possible loss, or eliminate the risks associated with market fluctuations.
Can I lose money by investing through Acorns?
Yes. Acorns makes investing accessible, but it cannot remove investment risk. The value of exchange-traded funds and other investments can rise or fall, meaning your account balance may be lower than the amount you deposited. Diversification may help reduce the impact of individual holdings, but it does not guarantee profits. Consider your goals, time horizon, and risk tolerance before investing.
Can I withdraw my money from Acorns whenever I want?
You can generally request withdrawals from eligible Acorns investment accounts, but the process may take several business days and can be affected by pending transactions, account verification, or unsettled investments. Retirement accounts may have tax consequences or penalties for certain withdrawals, while recurring deposits and transfers may require separate cancellation. Check the applicable account terms before moving money.

Acorns: Save & Invest Money
This site provides independent information about third-party apps and is not affiliated with, or the owner, developer, or distributor of, any app featured here. App names, logos, and trademarks belong to their respective owners. Developer details are provided for reference; please contact the developer directly via support@acorns.com, visit https://support.acorns.com/hc/en-us/articles/1500010364362-Acorns-Contact-Information, or review their https://www.acorns.com/privacy/.










